Loading...
Weekly Sector Review
For the week ended Sep 1, 2023

Focus on fundamentals: Sell investments based on value, not price

Published on 09/05/2023

One of the questions I am often asked is when to sell an investment. Part of the discipline of investing is monitoring each investment to keep abreast of its fundamentals. Here is a real-life example of an investment idea included in a piece entitled “Artificial Exuberance vs Artificial Intelligence,” published on June 12, 2023. In that piece I presented GEN Digital (GEN-NYSE), a case study of a technology stock trading at near-rock bottom valuation. I wrote:

“…GEN currently trades at a forward P/E multiple of less than 9X, while its median multiple over the past 9 years is 23X. On a discounted cash flow basis, I calculate that under a scenario of zero growth for the next 10 years the stock is undervalued by 35%.“

Seven weeks later, the company reported FQ1, 2024 on August 3, met consensus revenue expectations and beat consensus EPS expectations by a modest 2%. The share price increased by more than 10%, but this move was largely commensurate with an increase in its forward P/E valuation multiple, which is now 9.8X. Has the risk-adjusted return worsened? No. At time of writing, over the past nine years, 99% of the time it has traded at a higher forward P/E multiple, and 95% of the time it has traded at a higher multiple of forward-looking EV:EBITDA. The risk-adjusted return profile of the stock is still tilted significantly to the upside. With an improved consensus forecast for the company coming out of the most recent earnings report, the stock now appears undervalued by approximately 50% based on my discounted cash flow forecast, under a scenario of zero growth in earnings for the next 10 years.
The gap between fair value and price is key

Fundamentally, one should buy an asset if its fair value exceeds its current trading price. Ideally, the fair value should be significantly greater, providing a buffer against unknown risks and improbable, but catastrophic events. This “margin of safety” allows the investor to continue to hold the investment, even as he or she regularly re-assesses its fundamentals. As the marked-to-market value approaches fair value, the margin of safety declines and the investment becomes less attractive. If you have access to analyst reports, you may see that some make a point of highlighting the upside-downside risks. This is more instructive than the point estimates they often publish as price targets. Even better is if they provide a sensitivity table that allows you to translate your own expectations into an estimate of fair value.

Weekly sector recap

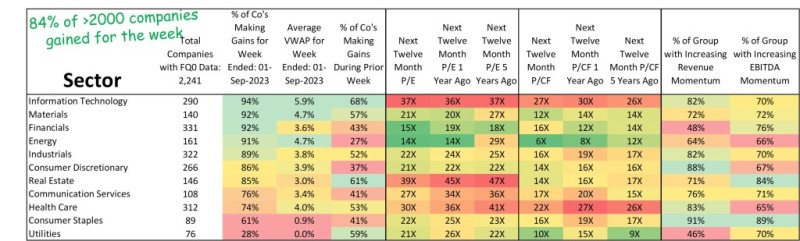
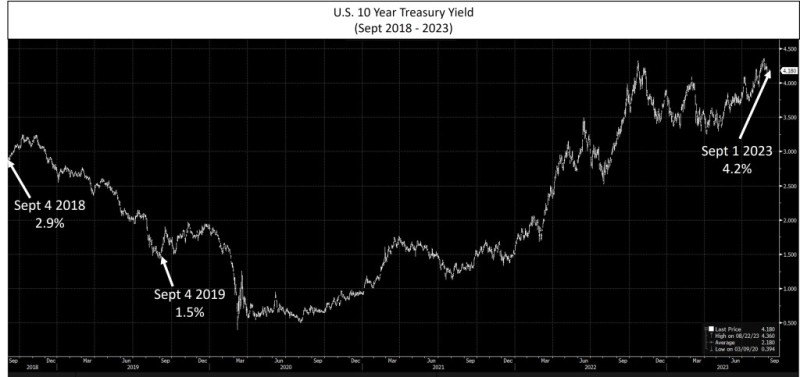
Last week, 84% of companies I cover posted price gains, and every sector improved except Utilities. The best-performing sector was Information Technology, with an overall gain of 5.9%. The forward P/E valuation multiple for Info Tech is 37X which is comparable to where it was 5 years ago, but remember that at that time, the risk-free rate (the 10 year Treasury yield) was 31% lower than it is now (2.9% instead of 4.2%), and one year later, on Sept 3, 2019 it had declined 48% (from 2.9% to 1.5%). My point is that at these levels investors must expect either parabolic growth or a profound decline in the risk-free rate.

Industries within Info Tech – The hottest of the hot

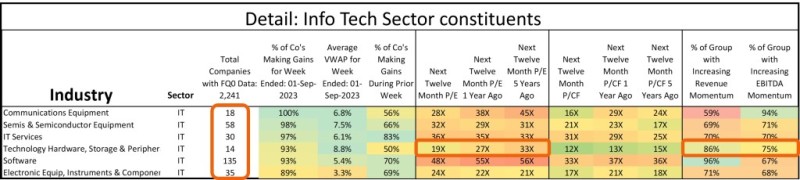
Breaking down the Info Tech sector into its constituent industries, we see that the largest industry, Software, is trading at 48X forward earnings, and the next-largest industry, Semiconductors & Semiconductor Equipment is trading at 32X. The cheapest industry is Technology Hardware, Storage & Peripherals, trading at 19X forward earnings compared to 33X five years’ ago, and featuring expected growth in revenue and EBITDA that is second-best of all six industries. Worth a look.

On February 28, 2012, SNC-Lavalin (now AtkinsRéalis) dropped 20%. That day, the Financial Post noted I "was the only analyst on Bay Street without a buy recommendation on SNC" going into that week—one of fifteen analysts covering the stock. I was at Macquarie Capital Markets at the time and wasn't trying to predict a scandal. The numbers simply didn't support the company's valuation.

That is the discipline underneath everything I do: see the world as it is, not as I want it to be. Most investing mistakes are wishes dressed up as analysis: the company has a story, the market has a mood, and investors have high hopes for their positions. But none of that changes what the company's cash flows are actually worth. I work from the evidence. I say what it shows even when it's unwelcome, and when it turns against me, I act on it rather than argue with it. Today, I'm a discretionary portfolio manager, and my own money is invested in the same strategies I run for clients. When markets are hard, I feel it in my own account. When a thesis works, we benefit together. I'll tell you what I own, why I own it, and what would change my mind.

How I invest: I run a quantitative model across thousands of North American stocks and dozens of international markets. I flag companies trading near the bottom of their historical valuation range, then read the filings to find out why. I look for a cheap price with a reason for the fundamentals to turn: a commodity at trough prices, a balance sheet being repaired, an insider putting up his own money. Before I buy, I write down the risks and what would make me sell. I sell when the risk-adjusted return is gone, not because the stock has gone up. I've posted these decisions publicly for years—see the time-stamped entries below.

Before managing money, I spent more than fifteen years as an equity analyst at National Bank Financial, Macquarie and others, then advised clients at Edward Jones and Foster & Associates. I'm now a portfolio manager with Designed Securities in Canada and registered in the U.S. through Designed Wealth USA, so I can work with clients on both sides of the border. I'm licensed for equities, derivatives and insurance, so I can plan around your whole financial life, not one account.

On weekends, I'm a gigging musician with a passion for '80s alternative (The Cure, Duran Duran, The Police, Tears for Fears and The Smiths).

Want a second opinion on your portfolio? Send me a message. I'll tell you, in plain language, what I'd keep, what I'd change and why. No pitch, no obligation, no charge.

Subscribe to the Chart Room for regular updates!

Disclaimer: The material contained herein is for information purposes only. This material is not intended to be relied upon as a forecast, research or investment advice, and is not to be construed as an offer or solicitation for the sale or purchase of securities, or as a recommendation for you to engage in any transaction involving Designed Wealth Management Inc. Investors should carefully consider the risks of investing in light of their investment objectives, risk tolerance and financial circumstances.