Loading...
Observations

Keep more of your growth. Get a U.S. Dollar RRSP or TFSA

Published on 04/05/2024
Loading...

Good advisors generate returns...and save you money


Good advisors provide value by:

  1. Generating returns, and
  2. Reducing costs

Much is written about returns, but not so much about reducing costs. A somewhat hidden cost is exchange rates, and reducing costs here can materially improve returns, as will be shown.

Setting up a U.S. dollar (USD) account for RRSPs and TFSAs can help save money because (1) U.S. investments are generally cheaper than Canadian investments, feature lower fees and are more varied in the opportunities they present; and (2) USD accounts effectively end the ongoing and wasteful cycle of exchange rate conversions.

Why own USD?


The Greenback still rules.

A currency must be well regarded to be used as part of a country's foreign exchange reserves. Globally, in 2022, the U.S. dollar accounted for almost 60% of foreign exchange reserves, while the Euro accounted for 20% and the Renminbi (the official currency of the People’s Republic of China) accounted for 3%. 

Much of the innovation that occurs on this planet happens in the U.S. Add to that the U.S. stock market, which is the largest in the world, and one can see why most growth ideas find their way to the U.S.A. to get funded.

To recap:

  1. The world wants the USD
  2. Many new growth ideas originate or get funded out of the U.S.

Now, imagine your advisor finds a new Artificial Intelligence investment (ABC) for you that is priced in USD, and you buy it in your regular, CAD-denominated TFSA. Later that year you sell it for a profit, and then use the proceeds to buy a quantum computing investment (XYZ) which is also priced in USD. The mismatch in currency leads to three different exchange-rate transactions (highlighted):

  1. ORDER: BUY USD ABC
  2. Account converts CAD to USD (~1.2% foreign exchange fee)
  3. BUY order executed
  4. 6 months later (investor sees a better opportunity)
  5. ORDER: SELL USD ABC
  6. SELL order executed
  7. Account converts USD proceeds back to CAD (~1.2% foreign exchange fee)
  8. ORDER: BUY USD XYZ
  9. Account converts CAD to USD (~1.2% foreign exchange fee)
  10. BUY order executed

Those fees add up. In and out, the investor may reduce returns by 3% or more due to exchange rate conversions.

Take a page from the Canada Pension Plan

If you think you don’t need to be thinking outside the border when it comes to investing, look at what our national pension fund, the Canada Pension Plan, is doing.

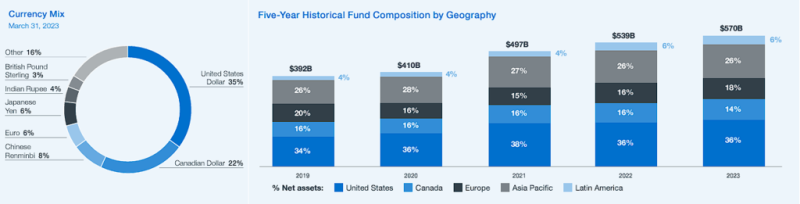
The Canada Pension Plan’s exposure to Canadian currency was 22% as at March 31, 2023, and its overall exposure to Canada was 14%.

Source: Canada Pension Plan 2023 Annual Report

Start a new habit

While working as a Bay Street investment analyst I was tasked with finding Canada-based growth companies, since Canadians were limited to how much foreign content they could have in their RRSPs and TFSAs. As part of my industry analysis, I regularly reviewed U.S. companies, and many times I found that the U.S. companies offered better value.

These days, while Canadian stocks account for less than 4% of the global equity market, Canadian investors typically allocate more than 50% of their total equity to Canada.

If you are looking for growth and don’t have a USD account, you should get one.

On February 28, 2012, SNC-Lavalin (now AtkinsRéalis) dropped 20%. That day, the Financial Post noted I "was the only analyst on Bay Street without a buy recommendation on SNC" going into that week—one of fifteen analysts covering the stock. I was at Macquarie Capital Markets at the time and wasn't trying to predict a scandal. The numbers simply didn't support the company's valuation.

That is the discipline underneath everything I do: see the world as it is, not as I want it to be. Most investing mistakes are wishes dressed up as analysis: the company has a story, the market has a mood, and investors have high hopes for their positions. But none of that changes what the company's cash flows are actually worth. I work from the evidence. I say what it shows even when it's unwelcome, and when it turns against me, I act on it rather than argue with it. Today, I'm a discretionary portfolio manager, and my own money is invested in the same strategies I run for clients. When markets are hard, I feel it in my own account. When a thesis works, we benefit together. I'll tell you what I own, why I own it, and what would change my mind.

How I invest: I run a quantitative model across thousands of North American stocks and dozens of international markets. I flag companies trading near the bottom of their historical valuation range, then read the filings to find out why. I look for a cheap price with a reason for the fundamentals to turn: a commodity at trough prices, a balance sheet being repaired, an insider putting up his own money. Before I buy, I write down the risks and what would make me sell. I sell when the risk-adjusted return is gone, not because the stock has gone up. I've posted these decisions publicly for years—see the time-stamped entries below.

Before managing money, I spent more than fifteen years as an equity analyst at National Bank Financial, Macquarie and others, then advised clients at Edward Jones and Foster & Associates. I'm now a portfolio manager with Designed Securities in Canada and registered in the U.S. through Designed Wealth USA, so I can work with clients on both sides of the border. I'm licensed for equities, derivatives and insurance, so I can plan around your whole financial life, not one account.

On weekends, I'm a gigging musician with a passion for '80s alternative (The Cure, Duran Duran, The Police, Tears for Fears and The Smiths).

Want a second opinion on your portfolio? Send me a message. I'll tell you, in plain language, what I'd keep, what I'd change and why. No pitch, no obligation, no charge.
Subscribe to the Chart Room for regular updates!

Disclaimer: The material contained herein is for information purposes only. This material is not intended to be relied upon as a forecast, research or investment advice, and is not to be construed as an offer or solicitation for the sale or purchase of securities, or as a recommendation for you to engage in any transaction involving Designed Wealth Management Inc. Investors should carefully consider the risks of investing in light of their investment objectives, risk tolerance and financial circumstances.